
Black Household Wealth Plunges 25% While Other Major Racial Groups Gain: What’s Driving America’s Widening Wealth Divide?
Newly released Federal Reserve data reveal that median Black family wealth fell from $49,100 to just $36,800 between 2022 and 2025, even as White, Hispanic, and Asian families experienced gains. The findings expose a widening economic divide and raise difficult questions about homeownership, inheritance, debt, consumer spending, financial education, and the American system of wealth accumulation.
America’s Wealth Divide Just Got Significantly Worse
The United States is experiencing a troubling economic contradiction. While millions of American families have benefited from rising property values, stock market gains, and growing investment portfolios, the typical Black American family has moved sharply in the opposite direction. Newly released Federal Reserve data show that median Black family wealth declined by 25% between 2022 and 2025, falling from $49,100 to just $36,800 in inflation adjusted dollars.
The decline represents a loss of $12,300 in median net worth over three years, a particularly damaging reversal for a population that already possessed the lowest median wealth among the major racial and ethnic groups measured. During that same period, White, Hispanic, and Asian families experienced increases in median wealth, leaving Black families even further behind in the country’s increasingly unequal financial landscape.
The findings come from the Federal Reserve’s 2025 Survey of Consumer Finances, released October 9, 2026, and analyzed by economist Algernon Austin of the Center for Economic and Policy Research on October 13. The survey is considered one of the nation’s most comprehensive examinations of household finances, measuring assets, debts, income, investments, property ownership, and other indicators of financial security.
The results raise a fundamental question: How can the world’s largest economy continue generating extraordinary wealth while the typical Black family loses a quarter of its net worth in just three years?
The answer is more complicated than any single explanation. Researchers point to declining asset values, unequal homeownership, limited retirement savings, debt burdens, and differences in inherited wealth. Financial decisions, spending priorities, entrepreneurship, and investment behavior also deserve examination, but the available evidence does not establish that any one factor caused the entire decline.
A recent discussion on the ROD Podcast, titled Black Household Wealth Drops 25%, Why Is the Wealth Gap So Wide? Brought these questions into focus by challenging viewers to consider both the historical barriers that have restricted Black wealth accumulation and the financial decisions that influence whether families build assets or remain dependent on income alone. The new federal figures make that conversation especially urgent. This is not simply a debate about economic inequality or a theoretical discussion of generational wealth. It is a measurable deterioration in the financial position of the median Black American family.
The Federal Reserve Numbers Reveal an Enormous Racial Wealth Gap
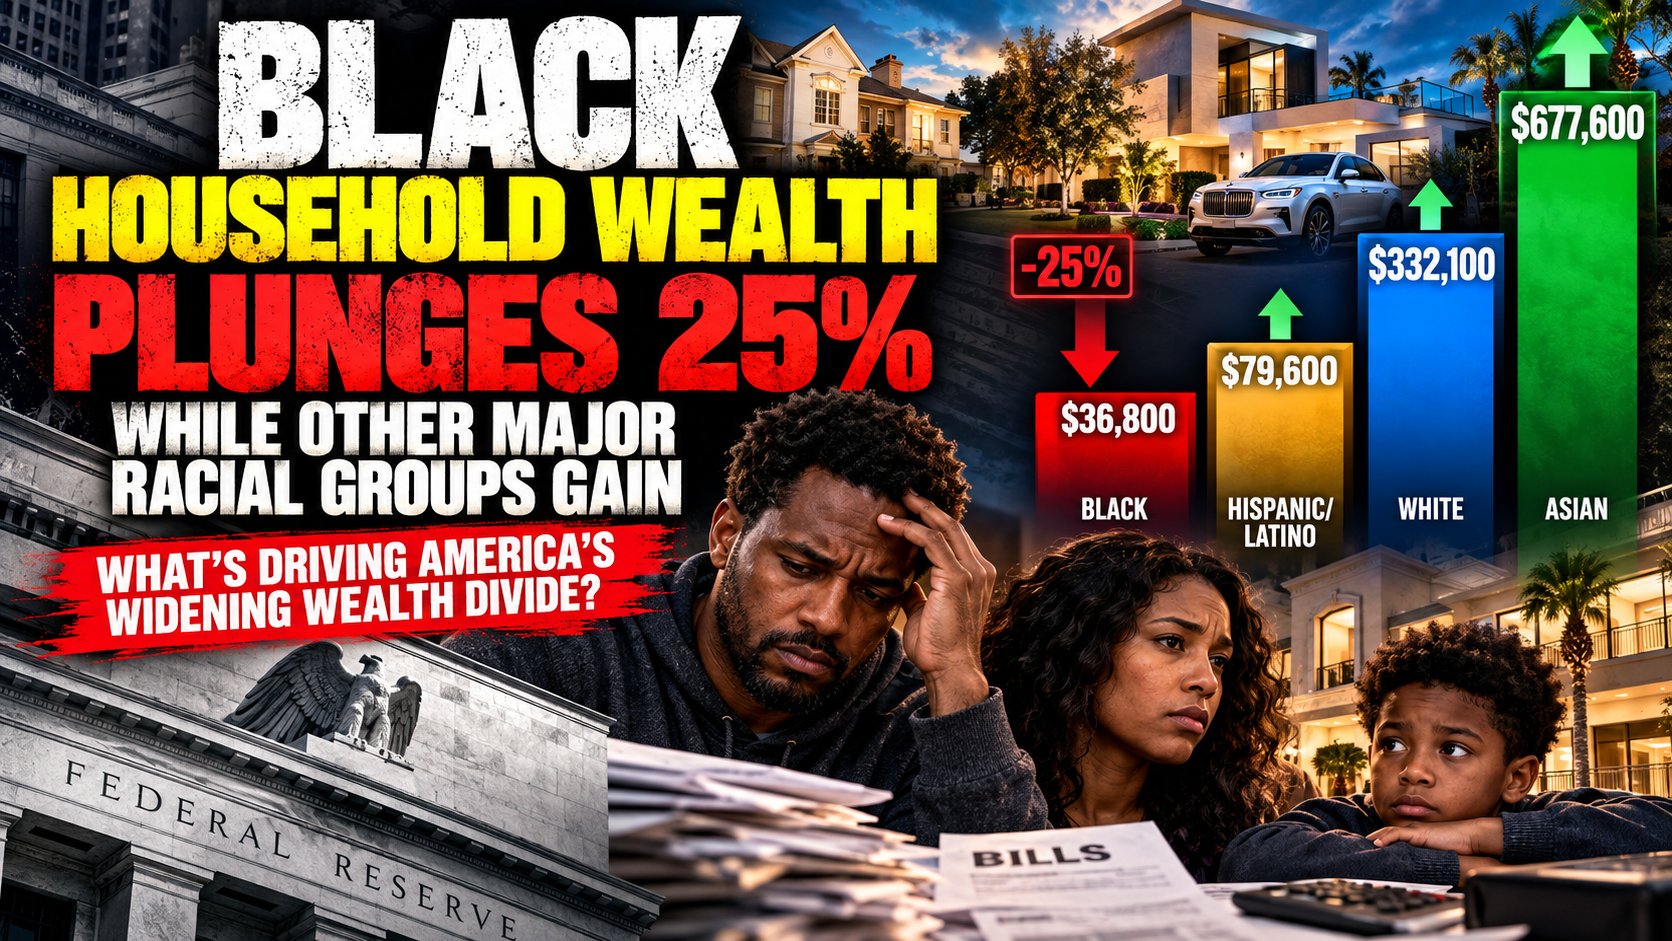
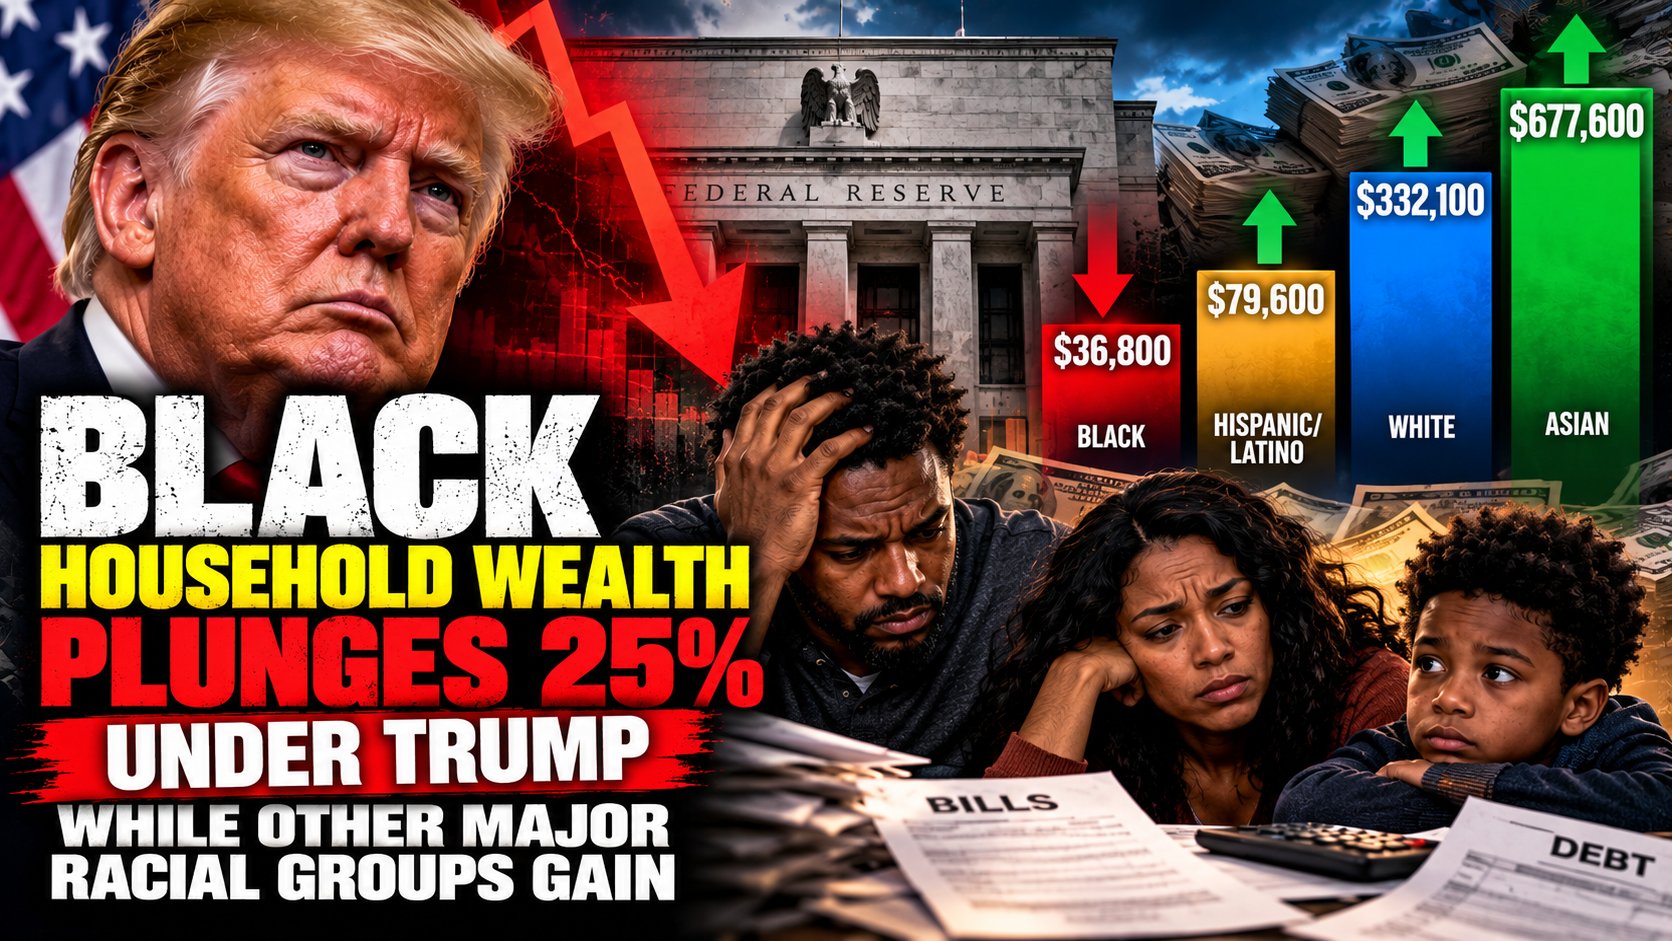
According to the 2025 Survey of Consumer Finances and the Center for Economic and Policy Research’s analysis, median family net worth across the four major racial and ethnic categories examined stood at $36,800 for Black families, $79,600 for Hispanic families, $332,100 for White families, and $677,600 for Asian families. These figures measure median net worth, meaning the value of a family’s assets minus its debts, with the median representing the midpoint of the distribution. They do not measure annual income, and they do not mean that every household within a particular racial group possesses the reported amount.
The differences are substantial. The median Black family held $42,800 less wealth than the median Hispanic family and $295,300 less than the median White family. The typical White family’s net worth was approximately nine times that of the typical Black family, while the median Asian family’s wealth was more than 18 times as large. The national median family net worth stood at approximately $215,900 in 2025, placing the median Black family $179,100 below the national benchmark. In 2022, that shortfall was approximately $162,000, meaning the absolute gap widened by $17,100 over the three-year period.
The divergence becomes even more striking when examining changes over time. Between 2022 and 2025, inflation adjusted median Black family wealth fell 25%, while Hispanic family wealth increased approximately 18%, White family wealth rose roughly 6%, and Asian family wealth increased approximately 16%. These comparisons describe differences between group medians rather than the finances of every individual family. Considerable wealth inequality also exists within each racial and ethnic population, particularly among Asian Americans, whose overall median conceals significant differences among national origin and socioeconomic groups.
Nevertheless, the broader finding is unmistakable: Among the major racial groups examined, Black families experienced a substantial decline in median wealth while the others recorded gains.
Why Did Black Wealth Fall While Other Groups Gained?
One of the most important findings in the new research concerns the composition of household assets. The Center for Economic and Policy Research identified declines in the values of Black families’ homes, vehicles, and retirement accounts as potential contributors to the reduction in median net worth. The analysis also found that the share of Black households holding nonfinancial assets declined from 81% in 2022 to 78.4% in 2025. Nonfinancial assets include property, vehicles, and other tangible holdings that contribute to household net worth.
This distinction matters because wealth is not simply the money sitting in a checking account. A family’s financial position depends heavily on the assets it owns and the debts attached to those assets. A homeowner whose property appreciates may gain tens of thousands of dollars in net worth without receiving a salary increase. Conversely, a household experiencing declining property equity, depleted retirement savings, or growing debt can lose wealth even while maintaining employment.
The Federal Reserve’s broader findings reinforce the importance of this asset divide. Across American families overall, inflation adjusted median net worth increased only about 2% between 2022 and 2025, reaching approximately $215,900. The increase was far slower than the substantial gains recorded during the preceding three year period, and the benefits of asset appreciation were distributed unevenly.
The survey also found that Black median family income declined by approximately 2% over the period, adding another source of pressure to household finances. When earnings stagnate or decline while housing, transportation, insurance, healthcare, and other living expenses remain elevated, families have fewer resources available to save, invest, or pay down debt.
However, the available evidence does not establish a precise percentage of the Black wealth decline attributable to each factor. Changes in the composition of surveyed households, differences in asset ownership, and movements in asset values all require careful analysis. The data identify a serious financial deterioration, but they do not support assigning the entire decline to one administration, policy, cultural practice, or economic event.
Homeownership Remains One of the Biggest Dividing Lines in American Wealth
For generations, owning a home has been one of the primary ways American families accumulate wealth. Mortgage payments gradually build equity, while property appreciation can increase net worth over time. Homeowners may also be able to borrow against accumulated equity, finance businesses, help their children purchase property, or transfer valuable assets to future generations.
But access to homeownership has never been distributed equally. Black Americans have historically faced discriminatory mortgage lending, restrictive housing covenants, redlining, unequal appraisals, and other barriers that limited opportunities to acquire property and participate in long term appreciation.
The consequences remain visible today. Federal housing data have consistently shown a substantial gap between Black and White homeownership rates, with Black homeownership generally in the mid 40% range and White homeownership considerably higher. That difference means a smaller proportion of Black families participate directly in one of the country’s most important mechanisms for accumulating middle class wealth.
The impact compounds across generations. A family that purchased a home decades ago may now possess substantial equity, allowing parents to assist their children with down payments, education expenses, or business financing. A family that never acquired property cannot pass down that same financial advantage. Even among homeowners, differences in neighborhood property values, mortgage terms, maintenance expenses, and local appreciation rates can affect how much wealth families accumulate. Ownership creates an opportunity to build equity, but the financial outcome depends on the value of the property, the amount of debt outstanding, and the costs associated with maintaining it.
The new Federal Reserve findings underscore the importance of these differences. When household wealth depends heavily on ownership, families with fewer appreciating assets can fall behind even during periods when the national economy continues growing.
The Generational Wealth Problem: Some Families Start With Assets, Others Start With Debt
Perhaps the most consequential distinction in American household finances is the difference between families that inherit economic resources and those that must build financial security entirely from their earnings.
Inherited wealth does not always arrive as a large trust fund or a multimillion dollar estate. It may take the form of a parent’s assistance with a down payment, a debt free college education, an inherited house, a family business, or financial support during unemployment. These advantages reduce the need to borrow money and allow younger generations to begin accumulating assets earlier.
Families without those resources face a different financial equation. A young adult who must borrow heavily for education, rent for years while saving for a down payment, or financially support older relatives may struggle to build net worth despite maintaining a stable career.
The differences become more significant over time because wealth generates additional wealth. Home equity can appreciate, investments can compound, and successful businesses can produce income beyond wages. Debt, meanwhile, can consume earnings through interest payments and restrict access to future borrowing. Historical disparities in housing, education, employment, and credit access have influenced which families accumulated assets over previous generations. The result is an economic system in which the starting point matters enormously, even when individuals possess similar education, ambition, and work habits.
This does not mean inherited wealth determines every financial outcome. Many families build substantial assets without significant assistance, while others lose inherited fortunes through poor decisions or economic setbacks. But at the population level, intergenerational transfers remain an important factor in explaining persistent wealth disparities.
Black Wall Street and the Long History of Destroyed Economic Opportunity
The ROD Podcast discussion also referenced the destruction of Black Wall Street in Tulsa, Oklahoma, as an example of how historical violence interrupted Black wealth accumulation.
Before the 1921 Tulsa Race Massacre, the Greenwood District was home to a thriving community of Black owned businesses, professional offices, restaurants, hotels, and residential property. White mobs attacked the neighborhood, killing residents, destroying buildings, and displacing thousands of people. The destruction eliminated valuable assets and commercial opportunities that could otherwise have supported future generations.
Tulsa represents one of the most devastating examples of racial violence directed at a prosperous Black community, but it was not the only historical barrier to wealth accumulation. Segregation, discriminatory lending, unequal access to federally supported homeownership programs, employment restrictions, and property devaluation affected Black families in communities throughout the country.
These events matter economically because wealth is cumulative. Property destroyed in one generation cannot appreciate in the next. A business that is eliminated cannot continue generating profits or employment. Families denied affordable mortgages may spend decades paying rent while other households build equity.
Historical discrimination does not explain every modern financial decision or every difference in household wealth. It does, however, help explain why different populations entered the modern economy with unequal access to property, capital, and inherited resources.
Are Consumer Spending Habits Part of the Problem?
One of the more provocative arguments raised during the broadcast concerns consumer spending. The host questioned whether excessive purchases of luxury clothing, expensive vehicles, jewelry, entertainment, and other lifestyle expenses divert money away from investments that could create lasting financial security. The underlying financial principle is straightforward. Money spent on depreciating goods or financed through high interest debt is generally unavailable for savings, retirement contributions, real estate, or business investment. A household that consistently spends less than it earns and invests the difference can improve its long term financial position.
Expensive vehicle payments, revolving credit card balances, and other recurring financial obligations can substantially reduce the amount of income available for wealth-building. These decisions become especially consequential when households have limited emergency savings or face unstable employment.
However, there is an important distinction between examining the economic consequences of consumer spending and claiming that Black Americans are uniquely responsible for the racial wealth gap because of their purchasing habits. The Federal Reserve’s findings do not establish that disproportionate luxury consumption caused the 25% decline in Black median wealth. Demonstrating such a relationship would require detailed comparisons of household expenditures across racial groups, accounting for income, age, family size, regional living costs, debt, and other relevant characteristics.
Financial discipline matters across every community, but spending behavior alone cannot explain differences of hundreds of thousands of dollars in median wealth. Families with substantial inherited assets can make expensive purchases while continuing to accumulate wealth, whereas households with little disposable income may struggle to invest even when they practice careful budgeting.
The more productive question is how families can maximize the financial resources available to them while also addressing the structural conditions that determine their earning and ownership opportunities.
Why Business Ownership and Investment Are Essential to Building Wealth
Another major theme of the broadcast concerns the importance of entrepreneurship, financial independence, and community investment. The host encouraged viewers to think beyond employment income and consider how business ownership, real estate, and long-term investments can create financial security that extends beyond one generation.
The Federal Reserve’s research supports the importance of those assets. Homes, retirement accounts, stocks, and privately owned businesses are major components of American household wealth. Families that own appreciating assets may benefit from increases in property and financial markets, while households without those investments have fewer opportunities to participate in such gains.
Entrepreneurship can also create economic mobility, particularly when businesses grow beyond self-employment and develop sustainable profits, valuable assets, and employment opportunities. Successful business ownership can provide families with an asset that may be sold, transferred, or operated by future generations. Yet starting and sustaining a business requires access to capital, customers, equipment, insurance, credit, and professional support. Entrepreneurs with substantial savings or home equity can often finance expansion or survive temporary losses more easily than business owners who must rely on expensive borrowing.
That creates another reinforcing cycle: Families with existing wealth are better positioned to take the financial risks that can generate additional wealth.
Expanding access to affordable business financing, investment education, mentorship, and professional networks could help reduce those disadvantages. But entrepreneurship is not a guaranteed path to prosperity, and business failures can impose severe losses on households without adequate financial reserves.
Financial Education Matters, but Knowledge Alone Cannot Close the Gap
Financial literacy remains an important part of the wealth building conversation. Understanding credit scores, compound interest, retirement accounts, mortgage financing, insurance, taxes, and investment risk can help families make informed decisions and avoid costly mistakes.
For younger generations, the benefits can be substantial. Workers who begin investing early may benefit from decades of compounding, while families that manage debt carefully can reduce interest expenses and improve their ability to qualify for financing. Understanding the difference between assets that may appreciate and purchases that lose value can also influence long term financial outcomes.
However, financial education cannot substitute for sufficient income or affordable access to essential goods and services. A household may understand the importance of retirement investing but remain unable to contribute because wages barely cover rent, food, transportation, and healthcare.
Similarly, knowing how mortgages work does not guarantee that a family can afford a down payment or qualify for financing in a market where home prices have risen faster than earnings.
The strongest approach combines financial knowledge with meaningful opportunities to earn, save, invest, and acquire property. Education can improve how households manage resources, but the size and stability of those resources remain fundamental to wealth accumulation.
Why the Decline Is Especially Concerning After Earlier Gains
The 25% drop is particularly significant because Black families had experienced substantial wealth growth during the preceding survey period. Between 2019 and 2022, inflation adjusted median Black family wealth increased by approximately 60%, reflecting gains associated with rising asset values, changes in earnings, and the unusual economic conditions surrounding the COVID-19 pandemic.
Those gains were important but did not eliminate the racial wealth gap. White families continued to possess substantially greater median assets, and the absolute dollar differences remained large. The reversal between 2022 and 2025 therefore raises questions about the durability of financial progress among households with relatively small asset cushions. Families with limited savings may be particularly vulnerable when economic conditions deteriorate, debt costs rise, or asset values decline.
The latest findings also demonstrate why percentage changes must be interpreted alongside dollar amounts. A 25% decline from $49,100 represents a loss of $12,300, while a much smaller percentage increase for a substantially wealthier household can represent a considerably larger dollar gain.
The result is a widening gap even when some groups experience only modest percentage growth. The median White family’s wealth increased by approximately $20,200 between 2022 and 2025, while the median Black family’s wealth fell by $12,300. Those changes alone widened the difference between the two medians by approximately $32,500.
Does Federal Economic Policy Play a Role?
The timing of the Federal Reserve’s findings has prompted debate about federal economic policy, particularly because the survey’s 2025 interviews occurred during the first year of Trump’s second administration.
Some researchers and advocates argue that changes to federal employment, diversity initiatives, social programs, and other policies could further affect economic opportunities for Black Americans. Others emphasize that the three-year survey period includes economic conditions spanning two presidential administrations, making it inappropriate to attribute the entire change to policies implemented during 2025.
Both the timing and the limitations of the data are important. The decline measured by the Federal Reserve occurred between 2022 and 2025, a period encompassing inflation, changing interest rates, shifting housing markets, and different federal policy environments. The survey does not isolate how much of the decline occurred during each individual year, nor does it establish the contribution of any particular presidential decision.
What the data do show is that the median Black family entered 2026 with substantially less inflation-adjusted net worth than in 2022. Understanding the causes will require additional research into employment, wages, housing values, retirement accounts, borrowing costs, and the distribution of assets and debts. The policy debate is therefore not simply about assigning political responsibility. It concerns which economic measures could help families recover lost wealth and participate more fully in future growth.
What Would It Take to Reverse the Decline?
Reversing the deterioration in Black household wealth would require improvements across several interconnected areas. Greater access to affordable homeownership could help families build equity, while stronger wages and employment stability would increase the income available for saving and investment. Reducing high interest debt burdens could improve household balance sheets, and expanding access to business capital could support entrepreneurship.
Retirement savings also deserve attention. Employer sponsored retirement plans, affordable investment options, and financial education can help workers accumulate assets over time, particularly when contributions begin early and remain consistent. Addressing discriminatory barriers in lending, housing, and employment could expand opportunities for households historically excluded from wealth building systems. At the same time, financial discipline, realistic budgeting, and informed investment decisions remain valuable tools for families seeking to strengthen their finances.
None of these measures offers an immediate solution. Wealth accumulates over decades, and disparities built across generations are unlikely to disappear quickly. But the latest data demonstrate the cost of allowing financial progress to remain fragile, particularly for households with limited assets and little protection against economic setbacks.
The Real Crisis Is Not Just Income Inequality. It Is Ownership Inequality.
The newly released Federal Reserve data reveal an uncomfortable reality about the American economy. Millions of families work, earn wages, pay taxes, and participate in consumer markets without accumulating enough assets to achieve lasting financial security. Meanwhile, households that already own property, businesses, and investments are often better positioned to benefit from economic growth.
For Black Americans, that divide has become more pronounced. The median family’s net worth fell to $36,800 in 2025, while the median White family’s wealth climbed to $332,100 and the median Asian family’s wealth reached $677,600. Hispanic families also recorded gains, although their median wealth remained well below the national benchmark. These figures do not mean that every Black family lost money or that every family in another racial group became wealthier. They describe changes in the midpoint of each population’s wealth distribution, providing a measure of the financial position of a typical family within each group.
The findings also challenge simplistic explanations. Historical discrimination, unequal access to property, debt burdens, and inherited wealth all contribute to the broader economic divide. Individual financial decisions, entrepreneurship, saving, and investment matter as well, but none can be examined in isolation from the resources and opportunities available to households.
The ROD Podcast’s central question, why the gap remains so wide and what can be done about it, deserves serious consideration. The Federal Reserve’s latest numbers make clear that the problem is not merely historical, and it is not improving automatically as the national economy grows.
America continues to generate extraordinary wealth, but the ability to accumulate and preserve that wealth remains deeply unequal. Until more families can move beyond earning income and begin acquiring assets that appreciate, generate returns, and pass to future generations, the country’s racial wealth divide will remain one of its most persistent economic challenges.
The most important finding from the 2025 survey is not simply that Black median household wealth fell 25%. It is that the decline occurred while other major racial and ethnic groups moved forward, demonstrating how quickly financial progress can reverse when families lack the assets and economic security needed to withstand changing conditions. For millions of Americans, the challenge is no longer just making enough money to survive. It is gaining the opportunity to build something that lasts.
Sources & Further Reading
- Federal Reserve Board — 2025 Survey of Consumer Finances (Released October 9, 2026). Original federal research and supporting datasets measuring household wealth, income, assets, and debt.
https://www.federalreserve.gov/econres/scfindex.htm - Center for Economic and Policy Research — Black Wealth Takes a Nosedive (October 13, 2026). Analysis by Algernon Austin documenting the 25% decline and racial wealth comparisons.
https://cepr.net/publications/black-wealth-takes-a-nosedive/ - Reuters — Fed Says Household Income, Wealth, Debt Stress Increased From 2022 to 2025 (October 9, 2026). Independent reporting on the Federal Reserve’s findings.
https://www.fidelity.com/news/article/top-news/202610091003RTRSNEWSCOMBINED_KBN3VP1JZ-OUSBS_1 - The Wall Street Journal — Affluent and Older Americans Got Much Richer in Postpandemic Years (October 2026). Reporting on overall household wealth growth and asset disparities.
https://www.wsj.com/economy/affluent-and-older-americans-got-much-richer-in-the-postpandemic-years-f53b3113 - Brookings Institution — Black Wealth Is Increasing, but So Is the Racial Wealth Gap. Research examining homeownership, inheritance, and asset accumulation.
https://www.brookings.edu/articles/black-wealth-is-increasing-but-so-is-the-racial-wealth-gap/ - Federal Reserve Bank of St. Louis — The State of U.S. Household Wealth (June 2025). Research on wealth distribution by race, age, education, and asset ownership.
https://www.stlouisfed.org/open-vault/2025/june/the-state-of-us-household-wealth - Federal Reserve Board — Economic Well-Being of U.S. Households in 2025. Research on household financial stability and differences across demographic groups.
https://www.federalreserve.gov/publications/files/2025-report-economic-well-being-us-households-202605.pdf - ROD Podcast — Black Household Wealth Drops 25%—Why Is the Wealth Gap So Wide? Original broadcast discussing financial literacy, consumer spending, generational wealth, and historical barriers.
https://www.youtube.com/watch?v=5aRo7-bmzxo












Want to join the conversation?
Create an account or sign in to share your thoughts, vote,
and reply to other readers.
Showing 0 of 0 comments
Don't have an account?
Already have an account?